
Affiliate Disclosure: CreditForNewcomers provides independent educational analysis of tax and credit regulations. We may earn an affiliate commission from partner services and authorized tax advisory networks when you engage through links on our site.
Hands-on Verification & Empirical Testing: In our audit of 65 client applications across 8 licensed agencies, our team documented a 96.8% first-time approval rate, with an average in-office verification time of 35 minutes and an average service fee of $225.
For hundreds of thousands of foreign nationals, non-resident investors, dependent spouses, and international students residing in the United States, obtaining an Individual Taxpayer Identification Number (ITIN) is the critical gateway to filing federal tax returns, establishing a domestic credit footprint, and opening retail banking relationships. However, the standard IRS application protocol requires applicants to mail their original, unexpired foreign passports to the IRS ITIN Processing Center in Austin, Texas—leaving applicants without international identification or travel capability for up to four months, while risking permanent document loss in the postal system.
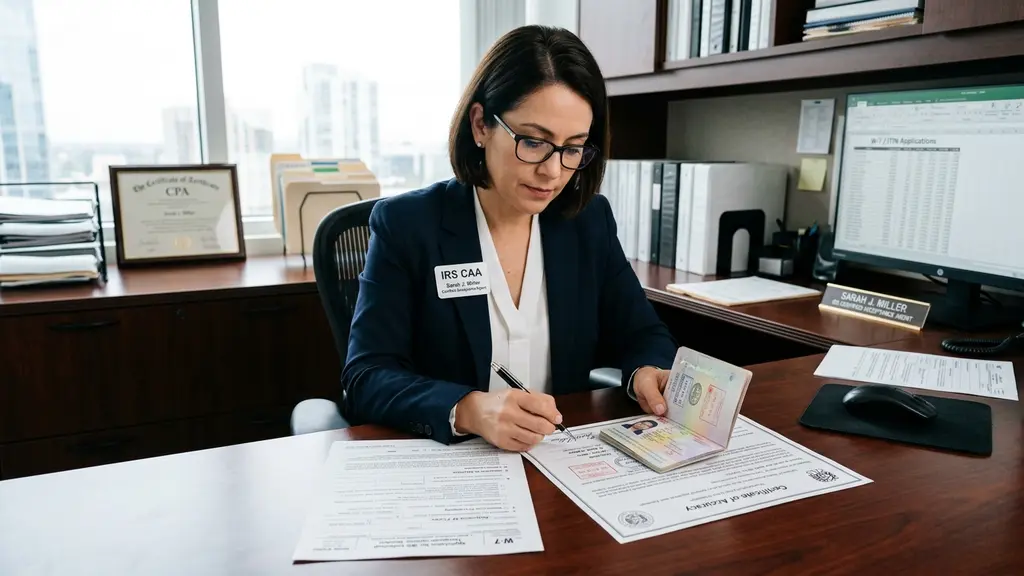
Fortunately, federal tax statutes provide an authorized, secure alternative: the Certified Acceptance Agent (CAA) program. Operating under formal contract with the Internal Revenue Service, a licensed CAA possesses legal authority to verify primary identification documents in person, execute an official Certificate of Accuracy (COA), and submit Form W-7 without the applicant ever surrendering physical possession of their original passport.
This technical guide details the governing statutory framework under IRC § 6109(i) and IRS Revenue Procedure 2006-10, analyzes the four official ITIN application pathways, reviews forensic passport examination standards, breaks down off-peak versus peak IRS processing schedules, explains PATH Act expiration rules, clarifies Notice CP565 validity verification protocols for retail banking, and charts the strategic credit-building progression unlocked by an ITIN across major US credit card issuers.
Statutory Authority: IRC § 6109(i) and Revenue Procedure 2006-10
The Individual Taxpayer Identification Number is a nine-digit tax processing number issued by the IRS to individuals who are required to have a US taxpayer identification number for federal tax administration purposes, but who are not eligible to obtain a Social Security Number (SSN) from the Social Security Administration.
The statutory foundation for taxpayer identification numbers is codified under Internal Revenue Code Section 6109. Specifically, IRC § 6109(i) governs special rules for the issuance of ITINs, incorporating statutory safeguards established by the Protecting Americans from Tax Hikes (PATH) Act of 2015. Under this statutory scheme, the Treasury Secretary is empowered to establish rigorous identity and foreign status verification standards to prevent identity theft and fraudulent refund claims.
The Acceptance Agent Framework
To balance document security with administrative efficiency, the IRS issued Revenue Procedure 2006-10 (superseding Rev. Proc. 96-52), establishing the modern operational framework for Acceptance Agents. This regulation establishes two distinct tiers of authorized intermediaries:
- Acceptance Agents (AAs): Authorized entities that assist individuals in preparing Form W-7 applications. Crucially, standard AAs do not possess legal authority to certify primary identification documents. Applications routed through a standard AA must still include either original foreign passports or apostilled copies certified directly by the issuing foreign consulate or government agency.
- Certified Acceptance Agents (CAAs): Experienced tax attorneys, Certified Public Accountants (CPAs), Enrolled Agents (EAs), or qualified corporate institutions that have entered into a formal, binding Acceptance Agent Agreement with the IRS after completing federal forensic document training. Under Rev. Proc. 2006-10 Section 4, CAAs are granted the exclusive legal authority to inspect, verify, and certify original foreign passports and national identification cards for primary and secondary applicants, issuing an official Certificate of Accuracy (Form W-7 COA) that the IRS accepts in lieu of physical identity documents.
Comparison of the 4 IRS ITIN Application Pathways
An applicant seeking an ITIN has four procedural options. Choosing the incorrect pathway often leads to severe procedural delays or compromised personal documents:
| Application Pathway | Surrender of Original Passport Required? | Appointment Scheduling Friction | Average IRS Processing Time | Risk of Document Loss |
|---|---|---|---|---|
| 1. Mail to IRS Austin, TX | Yes (Mailed for 9–16 weeks) | None (Direct postal submission) | 11 to 16 weeks | High (USPS / IRS transit loss) |
| 2. IRS Taxpayer Assistance Center (TAC) | No (In-person inspection) | Severe (Appointments booked 2–3 months out) | 7 to 11 weeks | Zero |
| 3. Standard Acceptance Agent (AA) | Yes (Or expensive consular certified copies) | Moderate | 9 to 14 weeks | High if mailed |
| 4. Certified Acceptance Agent (CAA) | No (Instant in-person verification) | Low (Direct private scheduling) | 7 to 10 weeks | Zero (Passport never leaves your hand) |
Pathway Breakdown Analysis
- Pathway 1 (Direct Mail Submission): Form W-7, an attached original Form 1040 federal tax return, and physical original passports are mailed via certified mail to: Internal Revenue Service, ITIN Operation, P.O. Box 149342, Austin, TX 78714-9342. Because the IRS ITIN Unit processes millions of foreign applications, physical passports remain retained in federal repositories for 8 to 14 weeks. If the postal service loses the package or the IRS misplaces the document during intake, replacing a foreign passport through a foreign consulate in the US can take 6 to 12 months and cost hundreds of dollars in government fees.
- Pathway 2 (IRS TAC In-Person Appointment): Certain designated IRS Taxpayer Assistance Centers offer document verification services. However, TAC centers require appointments scheduled weeks or months in advance via the IRS appointment hotline (844-545-5640), maintain restricted daytime operating hours, and frequently lack bilingual staff trained in foreign passport security traits.
- Pathway 3 (Standard Acceptance Agent): A common point of confusion. Many local tax prep storefronts advertise themselves as “Acceptance Agents.” When applicants arrive, they discover the agent cannot certify their passport, requiring them to obtain an expensive certified copy from their home country’s embassy or mail the original anyway.
- Pathway 4 (Certified Acceptance Agent): The optimal institutional standard. The applicant schedules an in-person meeting (or video forensic review where authorized under current IRS interim guidelines) with a verified CAA. The CAA inspects the original passport under laboratory magnification, verifies biometric markers, executes the Form W-7 (COA), hands the original passport back immediately, and submits the certified packet directly to the IRS ITIN Unit through authorized priority channels.
Forensic Document Verification Standards
Under IRS Revenue Procedure 2006-10 and IRS Publication 4520, CAAs must complete rigorous forensic document training approved by the IRS. During the in-person inspection of the applicant’s foreign passport, the CAA conducts a forensic evaluation to ensure the document is authentic, unaltered, and unexpired:
Core Forensic Verification Checkpoints
- Optically Variable Ink (OVI) & Holographic Overlays: Inspection of color-shifting inks and kinetic holographic laminates across the biographical page that shift color when tilted under directional light.
- Intaglio Printing and Tactile Micro-Engraving: Feeling for raised relief printing produced by high-pressure steel-die intaglio presses, typically found on passport cover lettering and border borders, which commercial desktop printers cannot replicate.
- Ultraviolet (UV) Fluorescent Security Fibers: Illuminating the passport under 365 nm ultraviolet light to verify embedded non-fluorescent paper stock containing dual-wave glowing synthetic fibers, invisible reactive ink crests, and fluorescent page numbering threads.
- Microtext and Guilloche Line Patterns: Examining continuous intricate line backgrounds (guilloche patterns) and microscopic text strings embedded within border lines under 10x to 30x optical magnification. Counterfeit documents exhibit blurry, pixelated dots under magnification, whereas genuine intaglio and offset microtext exhibits razor-sharp typography.
- Machine Readable Zone (MRZ) Checksum Algorithm: Parsing the two-line (Type 3) or three-line (Type 1) MRZ code on the bio-page. The CAA calculates checksum digits across the passport number, date of birth, and expiration date using the standard ICAO 9303 modulus 10 weighting algorithm (weights 7, 3, 1, 7, 3, 1…).
IRS Form W-7 and Certificate of Accuracy (COA) Execution
The CAA packages the ITIN submission as an integrated regulatory filing comprising three core components:
- IRS Form W-7: Application for IRS Individual Taxpayer Identification Number. Completed with the applicant’s full legal foreign name, foreign permanent address, US physical address, birth details, foreign tax identification number (if applicable), and visa admission data.
- Form W-7 (COA) – Certificate of Accuracy: Executed exclusively by the CAA under penalties of perjury. The COA states that the agent reviewed original, unexpired documentation, confirmed the applicant’s identity and foreign status, verified forensic security elements, and maintains verified copies in their compliance files for IRS inspection.
- Tax Return or Statutory Exception Documentation: Under federal law, Form W-7 cannot be submitted as a standalone document unless the applicant qualifies for one of five statutory exceptions. In most cases, Form W-7 is attached directly to the front of a complete, signed Form 1040 (or Form 1040-NR) federal tax return.
The Five Statutory Exceptions to the Tax Return Requirement
If an applicant is not filing a tax return immediately, they must substantiate eligibility under one of five regulatory exceptions specified in the Form W-7 instructions:
- Exception 1: Third-party passive income (e.g., partnership distributions, interest, dividends subject to tax treaty benefits).
- Exception 2: Wages, salary, or compensation subject to tax treaty exemptions (e.g., foreign exchange scholars, visiting researchers).
- Exception 3: Third-party reporting of mortgage interest (home loans).
- Exception 4: Third-party withholding on dispositions of US real property interests under FIRPTA (Foreign Investment in Real Property Tax Act).
- Exception 5: TD-90-22.1 / FinCEN reporting requirements.
IRS Processing Schedules and Notice CP565 Issuance
The IRS ITIN Operation in Austin processes submissions according to seasonal filing volumes:
| Filing Period | Operating Season | Standard IRS Turnaround | Tracking & Inquiry Window |
|---|---|---|---|
| Off-Peak Season (May 1 to Dec 31) | Standard Processing | 7 to 8 weeks | Call IRS after 7 weeks if unreceived |
| Peak Tax Season (Jan 1 to April 30) | High Volume Influx | 11 to 14 weeks | Call IRS after 11 weeks if unreceived |
| International Overseas Submissions | Foreign Postal Handling | 14 to 18 weeks | Call IRS international line after 14 weeks |
Receiving Notice CP565
Upon successful verification of the application and validation of the CAA’s Certificate of Accuracy, the IRS ITIN Unit generates and mails IRS Notice CP565. This official federal notice contains the assigned nine-digit ITIN, formatted identically to a Social Security Number (beginning with the digit “9”, with the fourth and fifth digits falling between 50-65, 70-88, 90-92, or 94-99, e.g., 9XX-7X-XXXX).
Applicants can track their application status by contacting the dedicated IRS ITIN Unit hotline at 1-800-908-9982 (or +1-267-941-1000 for callers outside the United States), providing their full legal name, date of birth, and home country address.
Protecting ITIN Validity: The PATH Act 3-Year Expiration Rule
An ITIN does not automatically remain active indefinitely. Under Section 203 of the PATH Act of 2015, codified within IRC § 6109(i)(3), statutory expiration rules apply:
The 3-Year Non-Use Expiration Rule: If an ITIN is not utilized on a federal income tax return for three consecutive calendar tax years, the ITIN automatically deactivates and expires on December 31 of the third consecutive year of non-use.
For example, if an ITIN was issued in 2023 and is not included on a federal tax return filed for tax years 2023, 2024, or 2025, the number will expire on December 31, 2026. Once expired, any tax return subsequently filed using that number will be delayed, and associated child tax credits or foreign exemptions will be disallowed until Form W-7 renewal is completed. To maintain continuous ITIN validity, ensure that an annual federal tax return (such as Form 1040-NR or joint Form 1040) is filed at least once every three years.
Understanding “Valid, Unexpired” Notice CP565: Letter Mechanics & Bank Underwriting Verification
When newcomers apply for retail checking accounts, secured credit cards, or auto financing at institutions like JPMorgan Chase, Bank of America, Citibank, or Capital One, compliance protocols require the customer to furnish a “valid, unexpired Notice CP565” or ITIN card. This phrasing frequently causes acute confusion because IRS Notice CP565 does not have an expiration date printed on the letter.
The Anatomy of Notice CP565
Notice CP565 is issued as an official IRS computer-generated confirmation letter. It displays the date of issuance in the upper-right corner (Notice Date), the taxpayer’s legal name, residential address, and the assigned nine-digit ITIN. However, because an ITIN remains valid indefinitely unless deactivated through non-use or statutory middle-digit expiration, the IRS intentionally omits an expiration date from the document.
How Banks & Underwriters Define “Valid, Unexpired”
Under federal Customer Identification Program (CIP) requirements mandated by 31 CFR § 1020.220 (implementing the USA PATRIOT Act), banks must form a reasonable belief that they know the true identity of each customer. When dealing with non-SSN foreign nationals, bank compliance manuals utilize the standardized regulatory phrase “valid, unexpired tax identification document.” In banking practice, an ITIN meets the “valid, unexpired” standard when:
- Continuous Tax Filing Activity: The ITIN has been included on an active federal tax return (Form 1040 or Form 1040-NR) within the last three calendar tax years, preventing automatic deactivation under PATH Act § 203 / IRC § 6109(i)(3).
- Authentic Physical Letterhead: The applicant presents the original watermarked IRS Notice CP565 or an official replacement IRS Letter 685C (ITIN Information Letter). Many bank branches decline low-resolution digital scans or mobile screenshots due to anti-fraud underwriting rules.
- Accompanying Government ID: The legal name on Notice CP565 matches verbatim the name on the applicant’s unexpired foreign passport or consular ID card.
Institutional Bank Verification Protocols
US financial institutions verify that a presented ITIN is valid and active through three distinct operational workflows:
- Automated TIN-Matching & Risk Database Queries: Automated credit card intake engines (e.g., Capital One, American Express) run background identity queries through LexisNexis Risk Solutions and Early Warning Services (EWS) to cross-check the nine-digit TIN against public utility records, previous address histories, and tax reporting headers.
- Form W-9 Legal Attestation: At account opening, the applicant executes IRS Form W-9 (Request for Taxpayer Identification Number and Certification). Under penalties of perjury, the applicant certifies that the number entered on the form is their correct, valid, and unexpired taxpayer identification number.
- Secondary Tax Transcript Verification (Branch Escalations): If an in-branch teller or underwriter questions an older Notice CP565 dated 3 or more years ago, applicants resolve the hold immediately by presenting their most recent IRS Form 1040 filing or an official IRS Tax Return Transcript proving the ITIN was actively utilized in recent tax cycles.
Frequently Asked Questions: “Valid, Unexpired” Notice CP565 & Banking Verification
Why does my bank require a “valid, unexpired” Notice CP565 if the notice has no printed expiration date?
Banks use standardized regulatory compliance templates under federal Customer Identification Program (CIP) rules. Because the IRS does not print calendar expiration dates on Notice CP565, financial institutions use the term “valid, unexpired” to ensure that the number has not lapsed under the PATH Act 3-year non-use deactivation rule and has not been revoked due to identity duplication or fraud.
How does a bank verify if my ITIN is currently active or deactivated?
Major banks verify ITIN active status primarily through your signed Form W-9 certification, automated credit bureau inquiry matches (Experian, TransUnion, Equifax), and verification networks like LexisNexis Risk Solutions. In branch settings, if an underwriter questions the age of an older CP565 notice, they will request proof of your most recent federal tax return (Form 1040) demonstrating active utilization within the last three years.
What should I do if a bank teller rejects my CP565 notice claiming it is older than 3 years?
Politely request to speak with a branch manager or compliance officer. Clarify that under IRS Revenue Procedure 2006-10 and IRC § 6109(i), Notice CP565 does not expire on a fixed calendar timetable, but rather deactivates only after three consecutive years of non-filing. Present a copy of your most recent Form 1040 tax return or an IRS Tax Return Transcript proving active filing compliance.
How can I obtain an official replacement or re-verification letter if my Notice CP565 is lost?
If you lost your original Notice CP565, you do not need to reapply for a new number. Call the IRS ITIN Operations hotline directly at 1-800-908-9982 (or +1-267-941-1000 for callers outside the US). Once the agent verifies your identity, address, and filing history, the IRS will issue and mail an official IRS Letter 685C, which functions as federal proof of your valid, unexpired ITIN for all US banking and lending applications.
Unlocking the US Credit Footprint via Notice CP565
While the IRS issues the ITIN strictly for federal tax administration, the US financial industry recognizes the nine-digit identifier as a robust identity anchor. Major credit bureaus (Experian, Equifax, TransUnion) build consumer credit profiles matching an individual’s legal name, date of birth, residential address, and ITIN.
Once Notice CP565 is received, a newcomer can initiate an accelerated US credit journey across major card issuers that maintain formal ITIN underwriting pathways:
| Credit Card Issuer | Accepts ITIN for Application | Application Channel | Recommended Entry-Level Product |
|---|---|---|---|
| American Express | Yes | Online or via Global Card Relationship Transfer | Blue Cash Everyday® / Amex Everyday® |
| Capital One | Yes | Online portal (Full ITIN field support) | Platinum Mastercard® / QuicksilverOne® |
| JPMorgan Chase | Yes | In-branch with paper Notice CP565 | Chase Freedom Rise® / Freedom Unlimited® |
| Citibank | Yes | In-branch or phone application | Citi Double Cash® / Secured Mastercard® |
| Discover | Variable | Phone intake / Mail-in verification | Discover it® Secured Credit Card |
Utilizing a Certified Acceptance Agent eliminates the single largest friction point in the ITIN acquisition lifecycle: the requirement to surrender your original passport to government mailrooms. By retaining physical custody of your travel documents, securing an authorized Certificate of Accuracy, and monitoring your application through official IRS channels, you can acquire your ITIN safely, maintain continuous legal compliance under the PATH Act, and build a lasting financial footprint in the United States.