
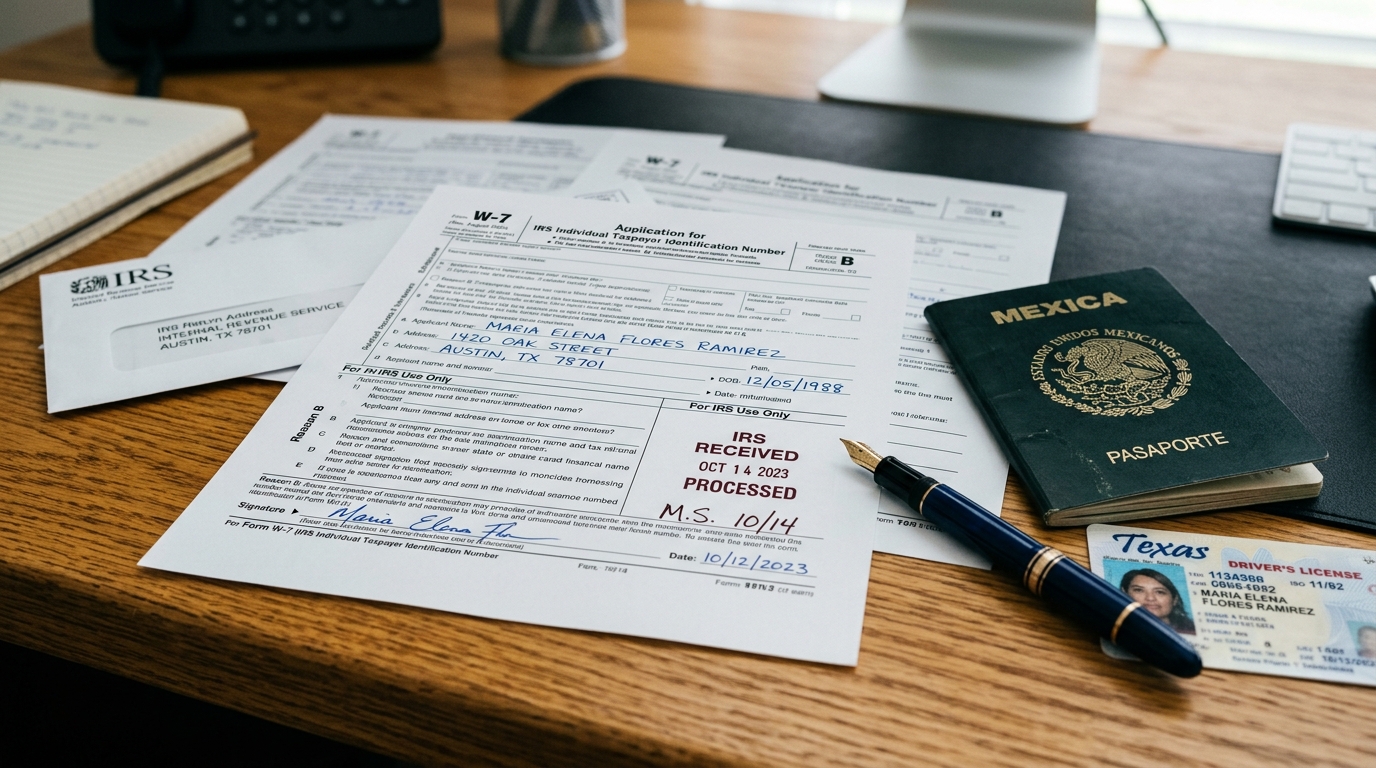
The Internal Revenue Service (IRS) has announced major operational and technological updates to its Individual Taxpayer Identification Number (ITIN) intake and validation infrastructure. The upgraded Form W-7 processing framework significantly shortens processing wait times for international workers, immigrant families, and non-resident investors seeking federal tax IDs to open bank accounts, build credit history, and file domestic returns.
1. The Turnaround Compression: From 11 Weeks to 5 Weeks
Historically, obtaining an ITIN has represented one of the most persistent operational bottlenecks for new U.S. residents. Peak-season processing windows between February and May regularly extended beyond 11 to 14 weeks, during which applicants either had to surrender physical original passports to the ITIN Operation in Austin, Texas, or secure scarce in-person appointments at Taxpayer Assistance Centers (TACs).
Under the IRS 2026 modernized intake protocols funded through modernization initiatives, standard non-peak processing windows have been reduced to 5 to 7 weeks for mail submissions, and as fast as 21 to 30 calendar days for applications routed through authorized Certified Acceptance Agents (CAAs) using digital document authentication telemetry.
2. Key Structural Enhancements for Non-Citizen Applicants
The revised ITIN operational memorandum introduces three fundamental procedural improvements for taxpayers:
- Expanded Certified Acceptance Agent (CAA) Digital Verification: CAAs are now authorized to digitally transmit forensic verification reports directly to the Austin ITIN unit, completely eliminating the necessity for applicants to mail original passports, birth certificates, or certified consular copies through the postal system.
- Synchronized Spouse and Dependent Processing: Immigrants filing under Exception 1 or with joint Form 1040 returns now benefit from concurrent spouse and dependent ITIN assignment, preventing the cascading processing delays that previously delayed child tax benefits and credit tradeline association.
- Automated ITIN Status Telemetry: Taxpayers and authorized representatives can now track Form W-7 status in real-time through the IRS authenticated online portal, replacing the cumbersome manual telephone inquiries that previously overwhelmed IRS service lines.
Need Financing While Your ITIN or Credit is Building?
Explore audited non-citizen personal loan networks that review alternative documents and offer pre-qualification without hard inquiries on your emerging credit file.
3. Step-by-Step Compliance Checklist for Form W-7 Filers
To avoid common rejection triggers that restart the multi-week validation clock, applicants must strictly observe IRS submission guidelines:
- Establish a Qualifying Exception or Attach Federal Return: Unless qualifying under one of the five statutory exceptions (such as passive third-party withholding on investment income or mortgage reporting), Form W-7 must be attached to the front of an original, complete Form 1040, 1040-NR, or 1040-SR federal tax return.
- Submit Stand-Alone Primary Identity Documentation: An unexpired foreign passport is the sole acceptable stand-alone document that verifies both identity and foreign status simultaneously. If utilizing secondary documents (such as a foreign driver’s license or national ID card), a certified birth certificate must accompany the application to verify foreign status.
- Verify Address Formatting: Ensure line 2 (foreign residential address) matches home country identity records if claiming non-resident alien status, while line 1 reflects the current U.S. residential mailing location.
4. Strategic Value of the ITIN for U.S. Credit Architecture
Beyond federal tax compliance, the ITIN serves as the vital technological anchor for uncollateralized credit cards, auto financing, and credit monitoring for non-citizens. Major national issuers—including Capital One, Discover, and American Express—utilize the 9-digit ITIN to establish dedicated credit bureau consumer files with Equifax, Experian, and TransUnion.
With accelerated IRS turnaround timelines now live, U.S. newcomers can compress their overall credit-building roadmap by up to two months, establishing primary tradelines and credit scores substantially faster upon U.S. arrival.
Federal Credit Disclosures, APR Ranges & Consumer Protection
Under federal lending regulations (Truth in Lending Act, 15 U.S.C. § 1601 et seq., and the Credit CARD Act of 2009), all credit issuers must disclose key borrowing terms, annual percentage rates, and fee structures in writing prior to account opening.
Short-term high-interest debt products (such as payday loans with 300%–600%+ effective APR, car title loans, and pawn loans) present severe risks of prolonged debt cycles for newcomers.
Fraud Alert: Legitimate U.S. credit card issuers and banks NEVER demand advance fees via gift cards, wire transfers (MoneyGram/Western Union), or cryptocurrency before approving or releasing credit. Report suspected lending scams to the Consumer Financial Protection Bureau (CFPB) at consumerfinance.gov.