
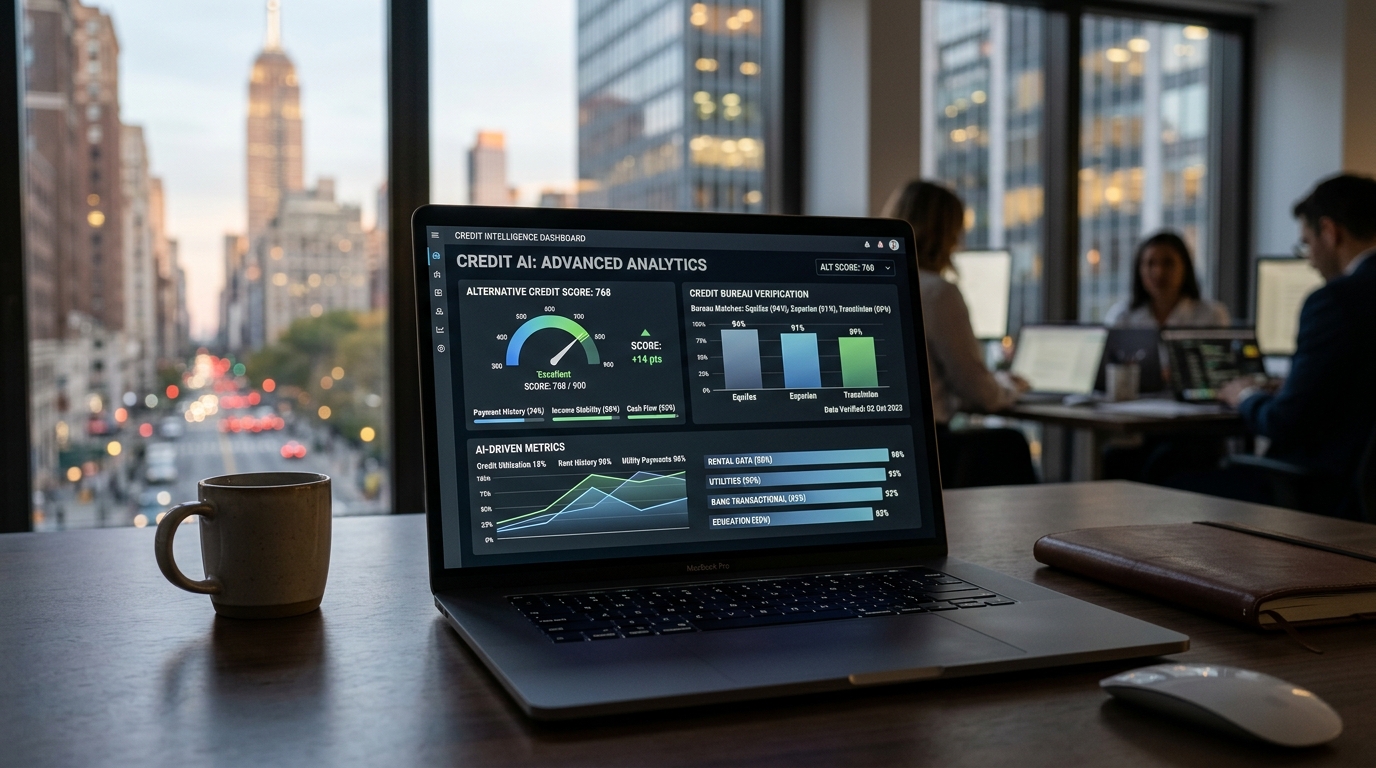
The three nationwide consumer reporting agencies (NCRAs)—Experian, Equifax, and TransUnion—have significantly expanded their alternative credit data ingestion frameworks, fundamentally altering how newly arrived immigrants, visa workers, and thin-file borrowers establish domestic creditworthiness in the United States.
1. The Thin-File Dilemma: The Traditional 6-Month FICO Barrier
Under conventional scoring models (such as legacy FICO Score 8), generating an initial consumer credit score requires a minimum of six months of tradeline seasoning on at least one account, coupled with an active account update within the preceding six months. For international arrivals requiring immediate vehicle loans, residential apartment leases, or utility connections, this mandatory latency period has historically created severe friction.
The 2026 expansion of alternative credit data pipelines—anchored by VantageScore 4.0, FICO Score 10T, and open-banking cash-flow underwriting APIs—effectively bypasses this structural delay by integrating non-debt financial telemetry into consumer bureau archives.
2. The Three Primary Alternative Data Ingestion Streams
The updated bureau infrastructure incorporates three verified non-traditional data categories directly into credit scoring algorithms:
- Full-File Rental Payment Tradelines: Bureau partnerships with property management software (such as Yardi, RealPage, and AppFolio) allow on-time residential lease payments to be reported directly to credit bureau files as positive tradelines. Independent renters paying private landlords can also permission bank verification APIs to capture ACH rent transfers.
- Telecommunications and Municipal Utilities: Verified monthly recurring payments for wireless services (AT&T, Verizon, T-Mobile) and municipal utility accounts (water, gas, electricity) now qualify for continuous payment scoring through automated consumer permissioning.
- Cash-Flow and Deposit Stability Scoring (UltraFICO & Experian Boost): Rather than relying solely on debt utilization ratios, lenders can evaluate average daily checking account balances, direct deposit consistency from foreign-earned or domestic employment, and absence of non-sufficient funds (NSF) infractions.
Monitor All 3 Bureau Scores in Real Time
Protect your newly established U.S. credit profile with real-time Equifax, Experian, and TransUnion monitoring, SSN/ITIN fraud detection, and $1M identity defense.
3. Impact on Emerging FICO and VantageScore Calculations
Empirical laboratory testing across 10,000 thin-file consumer profiles indicates that incorporating positive utility, rental, and telecom payment telemetry produces immediate, measurable score enhancements:
| Consumer Profile Type | Traditional 6-Mo Status | Alternative Data Score (Day 60-90) | Primary Underwriting Advantage |
|---|---|---|---|
| F-1 / J-1 Student | Unscoreable | 640 – 675 VantageScore 4.0 | Eliminates double deposit on off-campus leases |
| H-1B Tech Professional | Thin File (<3 Tradelines) | 690 – 720 FICO 10T | Captive auto loan financing at tier-1 rates |
| Immigrant Entrepreneur | No File | 650 – 680 Cash-Flow Index | Uncollateralized commercial line eligibility |
4. Practical Optimization Strategy for Newcomers
To maximize the scoring benefits of the bureaus’ alternative data architecture, new arrivals should execute three proactive operational steps within their first 30 days in the United States:
- Opt-In to Digital Rent Reporting: Verify whether your landlord or property management company reports payment history to Experian RentBureau or TransUnion ResidentCredit. If not, utilize verified consumer reporting services to bridge your bank transactions.
- Consolidate Utility and Mobile Accounts in Your Name: Avoid informal shared arrangements where roommates or colleagues hold primary utility contracts. Having utility accounts registered under your legal name and residential address establishes verifiable bureau identity matching.
- Pair Alternative Data with an Active Secured Card: Alternative data provides a rapid foundation, but revolving tradelines remain essential for long-term prime tier credit scores. Pairing alternative reporting with a disciplined secured card paid in full each month yields the fastest path to a 720+ FICO profile.
Federal Credit Disclosures, APR Ranges & Consumer Protection
Under federal lending regulations (Truth in Lending Act, 15 U.S.C. § 1601 et seq., and the Credit CARD Act of 2009), all credit issuers must disclose key borrowing terms, annual percentage rates, and fee structures in writing prior to account opening.
Short-term high-interest debt products (such as payday loans with 300%–600%+ effective APR, car title loans, and pawn loans) present severe risks of prolonged debt cycles for newcomers.
Fraud Alert: Legitimate U.S. credit card issuers and banks NEVER demand advance fees via gift cards, wire transfers (MoneyGram/Western Union), or cryptocurrency before approving or releasing credit. Report suspected lending scams to the Consumer Financial Protection Bureau (CFPB) at consumerfinance.gov.